Strength among slot suppliers, core casino customers and premium demand support the bank’s outlook, while weaker visitation, hotel performance and regulatory risks leave clear tests ahead.
Cindy F / Unsplash
Macquarie left G2E “cautiously optimistic” about the U.S. gaming industry, but the evidence behind that outlook points to a more uneven form of resilience than the headline suggests. Following more than 20 meetings at G2E, analyst Chad Beynon and his team remained constructive on the roughly $175 billion regulated U.S. gaming sector, particularly land-based slots. The bank cited resilient consumer demand, stable regional trends and continued strength from core customers despite broader economic concerns.
Slot Suppliers Have the Clearest Growth Case
Macquarie’s strongest conviction is around slot suppliers.
The bank expects industry slot gross gaming revenue to reach $104 billion in 2026, up 4% year over year, with gaming operations outpacing machine sales and leased revenue growing 4%. New cabinets, premium products and wider distribution across casino floors and digital channels came up repeatedly in its G2E meetings.
That gives suppliers more ways to grow than simply waiting for casino traffic to improve. They can win more floor space, expand leased-machine placements or take successful games into additional channels.
Light & Wonder is a good example. Management told Macquarie that AI has cut the time needed to port a game across platforms from six to eight weeks to about 17 hours. That builds on a strategy the company outlined earlier this year, when it said AI was helping to improve development speed and game portability across land-based and digital channels.
Its recent results also support the broader case for suppliers. Gaming Operations revenue rose 18% in the second quarter, while the company added 652 premium units. Machine sales were weaker, but management attributed that to project timing and said shipments should accelerate in the second half of the year.
Aristocrat told a similar story, pointing to new cabinets, premium products and digital distribution. The company expects its content pipeline and growing premium installed base to help it gain market share, while Aristocrat Interactive provides another avenue for growth.
That makes the supplier story less dependent on a broad consumer rebound than other parts of the industry. However, it is still tied to consumer demand. Casinos need to keep investing in their floors, and players need to keep spending. But suppliers have more ways to grow even if visitation remains soft.
Vegas Gaming and Hotel Performance Are Telling Different Stories
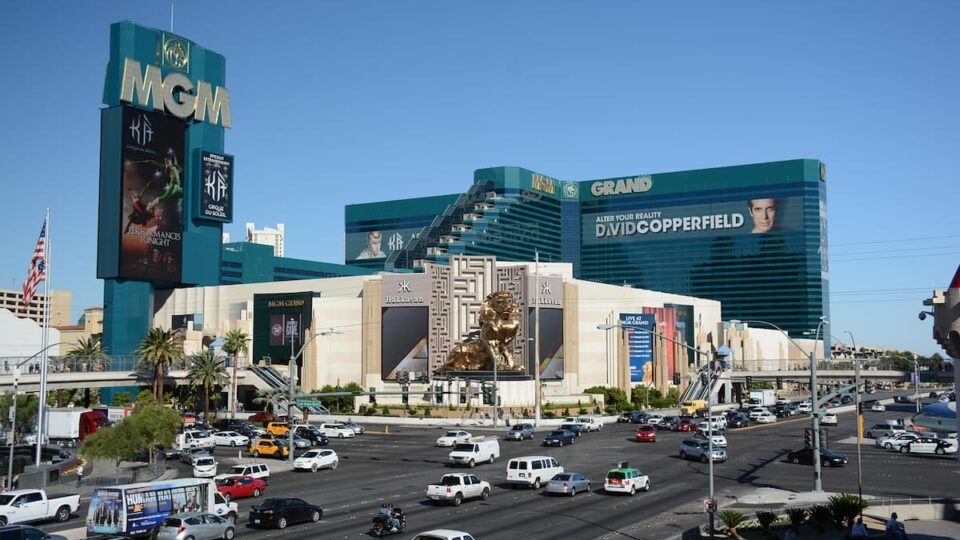
Las Vegas presents a harder case.
Macquarie reported visitation down 0.9% year-over-year quarter to date, while Strip revenue per available room (RevPAR) fell 6.9%. Operators nevertheless described gaming fundamentals as stable and attributed softer property performance largely to summer heat, outbound international travel and a return to more traditional seasonality.
That relatively modest visitation decline hides a sharp swing between the two available months: LVCVA data show visitation rose 2.7% in July year over year before falling 4.3% in August. In August, hotel occupancy was down 3.4 percentage points, and RevPAR was down 11.5%.
Yet Strip gaming revenue increased in both months, rising 3.6% in July and 0.7% in August. Through the first eight months of the year, visitation was nearly flat while Strip gaming revenue was up 2.9%.
Second-quarter results showed a similarly uneven picture. Caesars reported weaker Las Vegas revenue and EBITDA, while Boyd also saw softness in its Las Vegas businesses. MGM, however, grew Strip resort revenue and adjusted EBITDAR even as room revenue and RevPAR declined. Wynn’s Las Vegas EBITDAR fell, although casino revenue increased slightly.
That points to a more limited conclusion: gaming has held up better than the hotel and tourism side of Las Vegas, although results have varied by operator.
The seasonality argument still needs time to play out. Summer heat happens every year, and monthly results can also be affected by the calendar. If this is mostly a return to normal seasonal patterns rather than weaker demand, the next few months should make that clearer.
For now, the main question is whether gaming can continue to hold up if visitation remains soft.
Regional Gaming Shows the Same Divide
Regional casinos tell a similar story: weaker traffic has not necessarily translated into weaker spending.
Same-store regional gaming revenue increased 1.3% year over year in July before declining 1.9% in August, the first negative comparison since December 2025. Operators told Macquarie that core customer behavior remained resilient and promotional activity disciplined.
But visitation remains below historical levels, while feedback on lower-income customers was mixed. Macquarie’s own qualification is important: spending continues to hold up “for now.”
That may be one of the most important consumer signals in the report. Gaming revenue can remain resilient even with fewer visitors if customers who do show up continue to spend enough. But that is different from saying the underlying consumer base is expanding or even fully healthy.
August, therefore, matters. One negative month does not establish a trend, particularly in a business where monthly results can move with the calendar. But after the first negative comparison since December, September and October should provide a better indication of whether August was a temporary setback or whether weaker traffic is beginning to weigh on spending.
Prediction Markets Offer Growth Without Settling the Cannibalization Debate
Prediction markets are another example of growth driven by factors outside traditional customer demand.
For data providers such as Genius Sports and Sportradar, the opportunity extends beyond acquiring bettors. Both companies told Macquarie that one of the largest long-term opportunities could come from serving market makers with official data, pricing models, trading tools and settlement services.
Both companies have expanded deals with platforms such as Kalshi and Polymarket, with Sportradar executives saying on the latest earnings call that the sector would bring in “tens of millions” in revenue this year.
Companies like Flutter and DraftKings are pursuing both sides. Both have framed prediction markets as supplemental to sports betting, claiming they’ve seen limited cannibalization. Executives have also pointed to customer acquisition opportunities and the potential to explore market-making opportunities using their pricing capabilities.
Several companies told Macquarie they have seen limited evidence of cannibalization. But those are still early management assessments rather than the result of a detailed consumer study.
Current data suggest that prediction markets are helping operators reach customers in states where sports betting is not legal. Still, the longer-term question remains: do they expand the overall wagering market or eventually take spending from sportsbooks? Macquarie’s report cannot answer that yet.
That distinction becomes increasingly important as prediction-market volume grows and more sportsbook operators enter the sector.
Brazil Shows the Other Side of Regulatory Uncertainty
Brazil shows how quickly regulation can change an otherwise positive outlook.
After President Luiz Inácio Lula da Silva signed a provisional measure banning fixed-odds betting on Sept. 25, Flutter announced that it expects 2026 revenue to fall by approximately $70 million and adjusted EBITDA by $20 million if the provisional measure remains in effect for the rest of the year.
Inspired Entertainment estimated approximately $3 million of potential fourth-quarter revenue exposure. Entain, meanwhile, maintained its full-year EBITDA guidance but said it expects results to be toward the lower end of the range.
While both companies remain positive on their longer-term opportunities, those estimates show that regulatory uncertainty can have an immediate financial impact.
Prediction markets pose a similar uncertainty in the U.S. While the commercial opportunity is becoming easier to identify, the regulatory framework remains far less clear.
The Next Data Will Test Macquarie’s Thesis
Macquarie’s G2E takeaway is not that every part of the industry is strong. The better-performing areas are the ones with other ways to grow: suppliers can take market share, data companies can sell into prediction markets and premium casino customers are still spending.
The weaker signals are harder to ignore. Las Vegas visitation is down, hotel performance has softened, regional traffic remains below historical levels, and lower-income consumers look more mixed.
That helps explain why Macquarie uses phrases like “so far,” “for now,” and “cautiously optimistic.”
The next regional revenue reports and operator earnings should show whether that caution is warranted. If traffic stays soft but gaming revenue holds, Macquarie’s thesis looks stronger. If spending starts to weaken as well, the resilience seen at G2E may prove narrower than it first appeared.